The 2024 Autumn Statement included a headline grabbing announcement that the government planned to introduce restrictions to Agricultural Property Relief (APR) and Business Property Relief (BPR) that could have a serious financial impact on farming families and owner managed businesses. There then followed well publicised lobbying by industry groups and professional bodies against the changes.
However, on 21 July 2025, HMRC published draft legislation, set to take effect from 6 April 2026 which marks a significant overhaul of the Inheritance Tax (IHT) regime with no substantive changes to the proposed cap which was initially announced.
Key changes at glance
- The introduction of a £1 million “100% relief allowance” that can be claimed on a combined value of business and agricultural property. The allowance will be refreshed every 7 years.
- Relief above £1 million will be reduced to 50%, rather than the current unlimited rate of 100%.
- The £1m allowance will not be transferable between spouses. This was despite requests from professional bodies as part of the consultation process.
- Shares listed on the AIM market will only qualify for 50% BPR, removing full relief.
- Trusts will have a separate “100% trust relief allowance”, with its own rules and limits.
- Interest free Instalment payment option over 10 years for IHT will be extended to all APR/BPR-eligible property.
What does this mean for you?
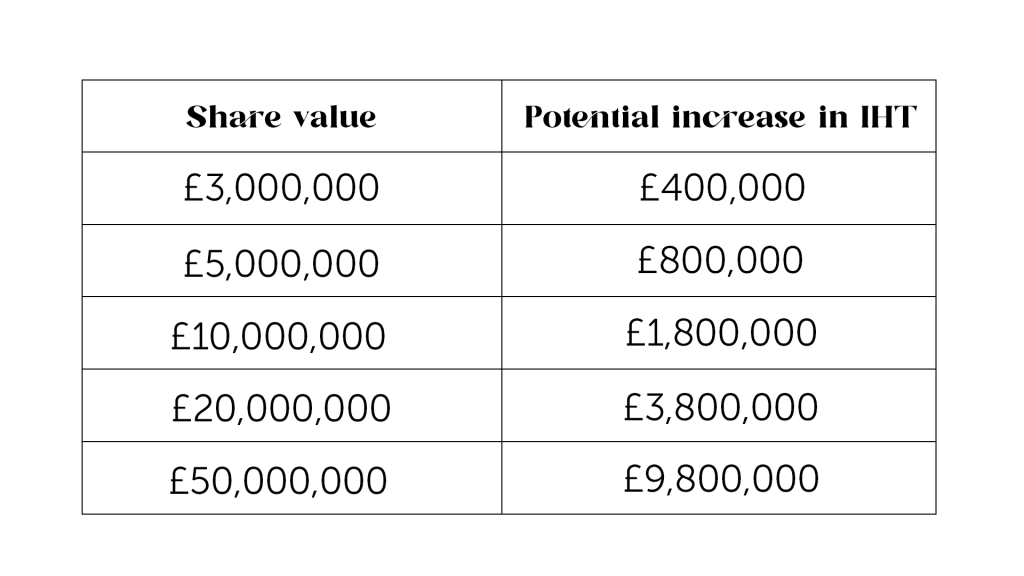
- The impact of the BPR changes will vary depending on the value of your business, but it could significantly increase the IHT exposure of your estate on death.
- Below are examples of the additional IHT charge that could arise in relation to shares in an unquoted trading company:
What are the next steps?
HMRC are inviting comments on the draft legislation until 15 September 2025 through a technical consultation, so it’s possible that changes will be made before the final rules are introduced. However, the recent announcement is a strong indication that the proposed changes will go ahead mostly as expected, including the transitional provisions which will apply to certain actions taken between 30 October 2024 and 5 April 2026.
With the reforms set to take effect in April 2026, now is the time to:
- Assess your estate and quantify IHT exposure, especially if you rely heavily on APR/BPR.
- Revisit your will and that of your spouse to ensure that the 100% allowance is maximised
- Assess trust structures and their exposure to the new trust relief limits.
- Consider making gifts now especially in light of recent rumours regarding potential restrictions being introduced at the next Autumn statement which is expected at the end of October.
- Take professional advice on suitable state planning
Get in touch at enquiries@cowgills.co.uk if you need further advice.

